
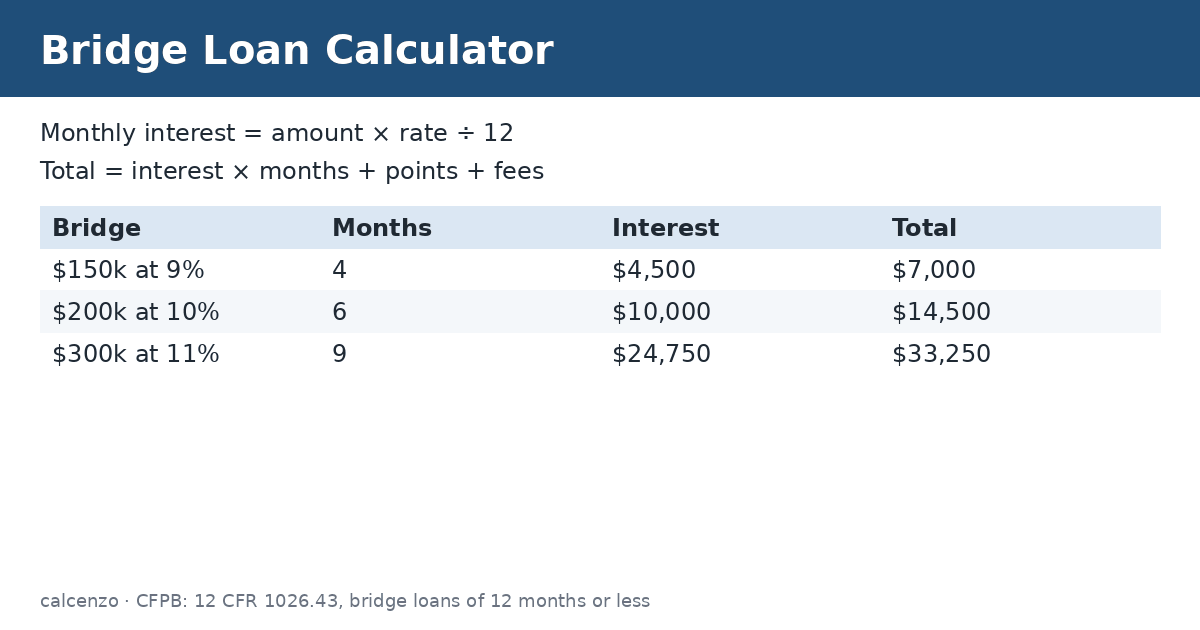
A bridge loan calculator estimates what it costs to borrow against your current home for a few months so you can buy the next one before the first sells. Formula: Monthly interest = amount × rate ÷ 12; total cost = monthly interest × months + amount × points + fees. A $200,000 bridge at 10% held for 6 months, with 1.5 points and $1,500 of fees, costs $14,500: $10,000 of interest, $3,000 of points and the fees.
On this page
How to use the bridge loan calculator
- Enter the amount you need to bridge, usually the down payment and closing costs on the new home.
- Enter the annual rate from your quote.
- Enter the number of months you expect to keep the loan. Be honest: this is the time until your current home sells and closes.
- Enter origination points as a percent and any other fees in dollars.
The bridge loan calculator returns the monthly interest-only payment, the interest for the whole hold, the dollar cost of the points, and the total.
What formula does the bridge loan calculator use?
Most bridge loans are short and interest only, so the math is simple. Monthly interest is the amount times the annual rate divided by 12. Interest for the hold is that figure times the months. Points are the amount times the point percentage, paid once. Add your other fees for the total.
The tool does not pay down principal. You repay the full balance in one lump sum, normally from the sale of the old home. That makes it a balloon-style loan, and the CFPB explains how balloon payments work and when they are allowed.
Bridge loan calculator worked example
Results from the bridge loan calculator:
| Bridge | Monthly interest | Interest for hold | Points | Fees | Total cost |
|---|---|---|---|---|---|
| $150,000, 9%, 4 months, 1 point | $1,125.00 | $4,500.00 | $1,500.00 | $1,000.00 | $7,000.00 |
| $200,000, 10%, 6 months, 1.5 points | $1,666.67 | $10,000.00 | $3,000.00 | $1,500.00 | $14,500.00 |
| $300,000, 11%, 9 months, 2 points | $2,750.00 | $24,750.00 | $6,000.00 | $2,500.00 | $33,250.00 |
Time is the big lever. If the $200,000 example takes 12 months instead of 6, interest doubles to $20,000 and the total climbs to $24,500. The points and fees stay the same, so a short hold makes them a bigger share of the cost.
How federal rules treat bridge loans
Under Regulation Z, a temporary or bridge loan with a term of 12 months or less is exempt from the ability-to-repay rules in 12 CFR 1026.43(c) through (f). The official example is a loan to buy a new home when you plan to sell your current one within 12 months. In plain terms, the lender does not have to run the same full ability-to-repay test it uses for a regular mortgage, so the burden is on you to check that you can carry both homes.
That is why it pays to run the bridge loan calculator with a longer hold than you expect. If the first home sits for months, you may pay the old mortgage, the new mortgage and the bridge interest at the same time.
Alternatives to a bridge loan
Before you sign, compare a few other options. A home equity loan or line of credit on the current home can cost less, though you may need to apply before you list it. Some buyers make an offer that depends on selling their home first. Others rent for a short time after selling. Our home equity loan calculator lets you price the first option, and you can put the result next to the bridge loan calculator number.
Ask every lender for the same details: rate, points, fees, the longest term allowed, any extension fee, and whether there is a prepayment penalty if your home sells early.
Common mistakes to avoid
A common mistake is forgetting that you may still owe payments on the old mortgage while the bridge is open. Add that payment and the new mortgage payment to the monthly interest shown here to see the true monthly cash need. Another is assuming the home will sell at list price; if it sells for less, the money left to repay the bridge shrinks.
Estimates for education only, not tax, legal or financial advice. Check current rules with the tax authority or a qualified adviser.
Related converters and calculators
Related calculators:
- Home equity loan calculator: borrow against equity
- Mortgage calculator: new home payment
- Construction loan calculator: interest during a build
Sources
CFPB: 12 CFR 1026.43, bridge loans of 12 months or less; CFPB: What is a balloon payment?; CFPB: How should I use lender credits and points?; CFPB: What is a prepayment penalty?.
Questions about this calculator
What is a bridge loan?
A short-term loan, often secured by your current home, that lets you buy a new home before the old one sells. You repay it from the sale.
How much does a bridge loan cost?
Interest for the months you hold it plus points and fees. A $200,000 bridge at 10% for 6 months with 1.5 points and $1,500 of fees costs about $14,500.
Are bridge loans interest only?
Many are. The monthly payment covers interest and the balance is repaid in one sum when your home sells.
How long can a bridge loan last?
Terms are commonly a year or less. Regulation Z treats bridge loans of 12 months or less differently from regular mortgages.
What if my house does not sell in time?
You keep paying interest and may face extension fees, while still paying both mortgages. Plan for a longer hold than you expect.
Check the assumptions and units before relying on a result. Financial, tax and health estimates do not replace advice for your individual circumstances.
Report a calculation issue