
A hard money loan calculator adds up the payment, interest and points on a short-term investor loan secured by property rather than by your income. Formula: Interest only: payment = amount × rate ÷ 12; amortizing: payment = PMT(rate ÷ 12, months, amount); cost = total interest + amount × points. A $250,000 loan at 12% for 12 months with 2 points costs $35,000 interest-only ($2,500 a month) or $21,546.37 if it fully amortizes ($22,212.20 a month).
On this page
How to use the hard money loan calculator
- Enter the loan amount the lender will fund.
- Enter the annual interest rate and the term in months.
- Enter the points charged at closing, as a percent of the loan.
- Choose interest only or fully amortizing.
The hard money loan calculator shows the monthly payment, interest over the term, the dollar amount of the points, and interest plus points together.
What formula does the hard money loan calculator use?
For interest-only loans, the payment is the amount times the rate divided by 12, and you repay the full balance at the end. For fully amortizing loans, the tool uses the standard payment formula P = L × r ÷ (1 − (1 + r)−n), with r the monthly rate and n the months. Points are a one-time charge: the amount times the point percent.
Most short investor loans are interest only, with the whole balance due at the end, which is a balloon payment.
Hard money loan calculator worked example
Results from the hard money loan calculator:
| Loan | Style | Monthly payment | Interest | Points | Interest plus points |
|---|---|---|---|---|---|
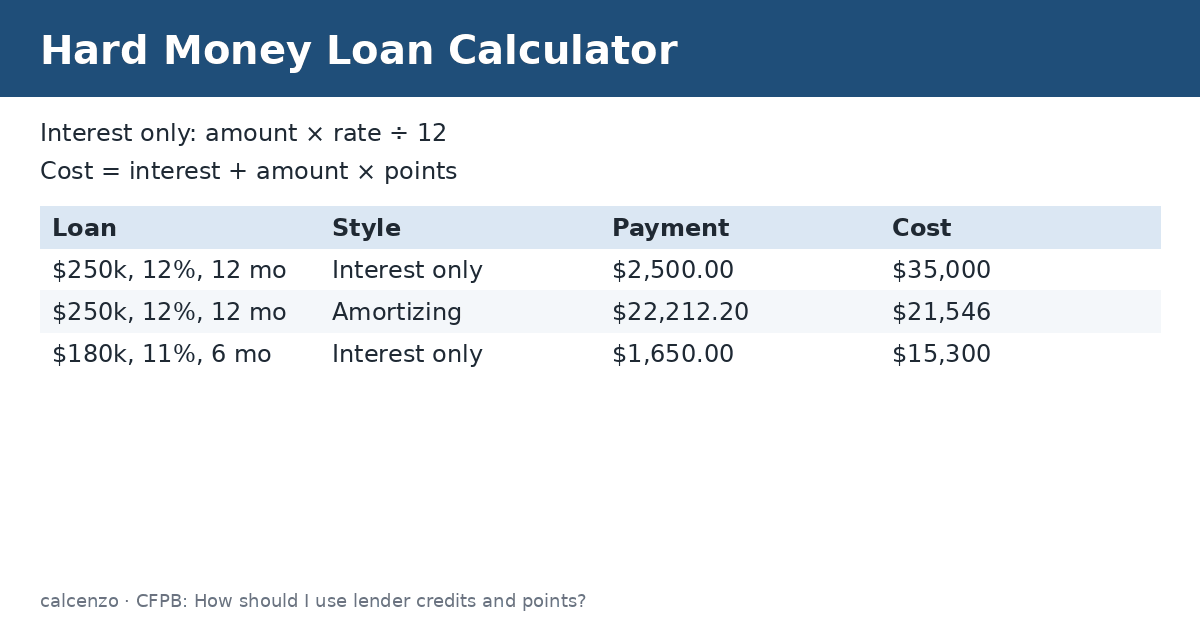
| $250,000, 12%, 12 months, 2 points | Interest only | $2,500.00 | $30,000.00 | $5,000.00 | $35,000.00 |
| $250,000, 12%, 12 months, 2 points | Amortizing | $22,212.20 | $16,546.37 | $5,000.00 | $21,546.37 |
| $180,000, 11%, 6 months, 3 points | Interest only | $1,650.00 | $9,900.00 | $5,400.00 | $15,300.00 |
The amortizing loan costs less interest because you pay the balance down each month, but the payment is nearly nine times larger. That is why flippers almost always take interest-only terms and repay from the sale.
Why points matter so much on short loans
Points are paid up front no matter how long you keep the loan. On the six-month example, 3 points cost $5,400, more than half of the $9,900 of interest. If you sell in three months, the points are an even bigger share. The CFPB explains that points are charged as a percent of the loan amount; one point is 1%.
When you compare lenders, run the hard money loan calculator for each quote using the months you really expect to need. A lower rate with more points can cost more on a short project.
Using the result in a flip budget
Carry the interest plus points into your deal analysis as a holding cost. Add extension fees if the lender charges them, and ask whether there is a prepayment penalty or a minimum interest period. Our ROI calculator shows how financing costs change your return.
Business-purpose loans on investment property may not carry the same consumer disclosures as a home mortgage, so read the note and ask for every fee in writing.
Common mistakes to avoid
The most common mistake is using the term on the loan papers instead of the time you will really hold the property. Rehab work often runs late, sales take longer than planned, and each extra month adds a full interest payment. Another is forgetting that some lenders hold back part of the loan and release it in draws, while charging interest on the full amount from day one. Ask how interest is charged before you sign.
A third mistake is leaving out the fees that are not called points, such as underwriting, processing, draw inspection and wire fees. Add them to the points field as a percent, or keep a separate list, so the total cost from the hard money loan calculator is complete.
Estimates for education only, not tax, legal or financial advice. Check current rules with the tax authority or a qualified adviser.
Related converters and calculators
Related calculators:
- ROI calculator: return on the deal
- DSCR loan calculator: rental refinance
- Business loan calculator: term loan payment
Sources
CFPB: How should I use lender credits and points?; CFPB: What is a balloon payment?; CFPB: What is a prepayment penalty?.
Questions about this calculator
What is a hard money loan?
A short-term loan from a private or specialty lender, secured mainly by the property and often used for flips and quick purchases.
How are hard money loan payments calculated?
Interest-only payments are amount × rate ÷ 12. Amortizing payments use the standard loan payment formula.
What do points cost on a hard money loan?
Each point is 1% of the loan. Two points on $250,000 is $5,000, paid at closing.
Why are most hard money loans interest only?
Investors plan to repay from a sale or refinance, so interest-only keeps the monthly payment low during the project.
Is this a lender quote?
No. It uses the rate, term and points you enter. Get written terms from the lender.
Check the assumptions and units before relying on a result. Financial, tax and health estimates do not replace advice for your individual circumstances.
Report a calculation issue