
A down payment calculator shows how much cash you need upfront to buy a home at a chosen down payment percentage, and how much more you need to save. Formula: Need = price × pct / 100. Remaining = max(0, need – saved). Headline is the target need. 20% down on a $400,000 home is $80,000; with $30,000 saved, you still need $50,000.
On this page
How to use the down payment calculator
- Enter the home price.
- Enter the down payment percentage.
- Enter how much you have saved.
- Read the down payment target and the amount still needed.
How the down payment calculator works
A down payment is the part of a home’s price you pay upfront in cash; a mortgage covers the rest. The down payment calculator multiplies the price by the percentage you plan to put down and subtracts what you have already saved.
- Down payment = home price × down payment %
- Still needed = down payment − savings (never below zero)
- Loan amount = home price − down payment
Down payment calculator worked example
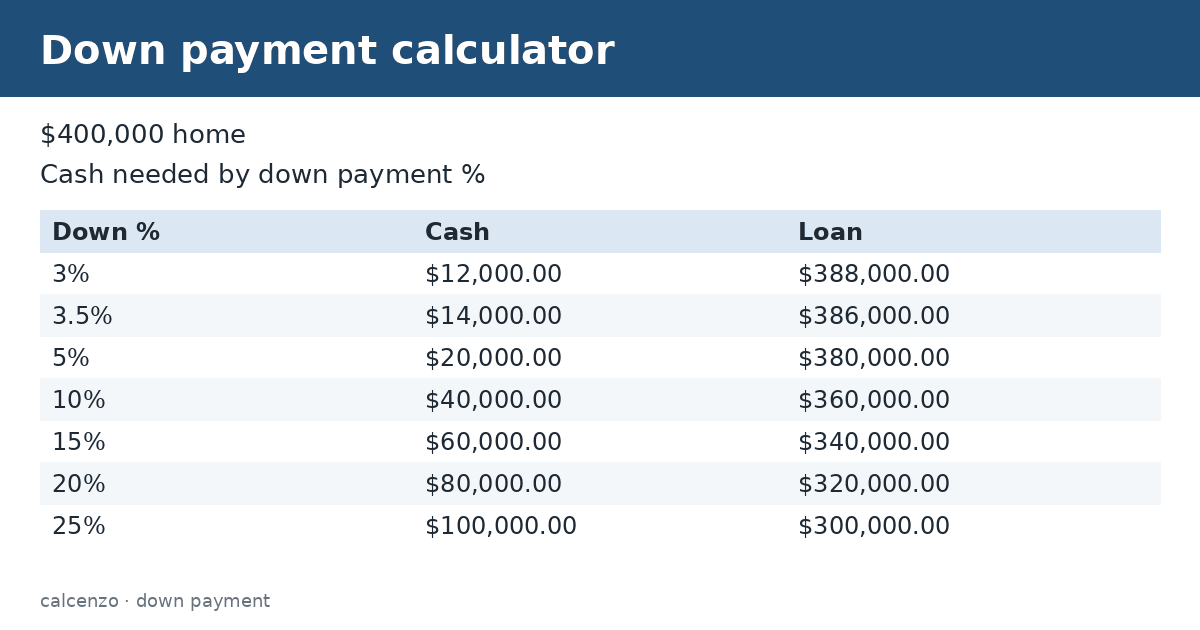
For a $400,000 home with 20% down, the down payment is $80,000 and the loan is $320,000. If you have saved $30,000, you still need $50,000. At 10% down, the target falls to $40,000, but the loan rises to $360,000.
| Down payment | Cash needed on $400,000 | Loan amount |
|---|---|---|
| 3% | $12,000.00 | $388,000.00 |
| 3.5% | $14,000.00 | $386,000.00 |
| 5% | $20,000.00 | $380,000.00 |
| 10% | $40,000.00 | $360,000.00 |
| 15% | $60,000.00 | $340,000.00 |
| 20% | $80,000.00 | $320,000.00 |
| 25% | $100,000.00 | $300,000.00 |
Do you need 20% down?
No. Many loans allow much less. However, the CFPB explains that if you put down less than 20% on a conventional loan, the lender will usually require private mortgage insurance (PMI), which protects the lender and adds to your monthly cost. FHA loans charge their own mortgage insurance: an upfront premium of 1.75% of the base loan, plus an annual premium that is 0.55% for most 30-year loans with less than 5% down. VA and USDA loans have their own fees and may allow no down payment for eligible borrowers.
Larger vs smaller down payment
- Larger down payment: smaller loan, lower monthly payment, less interest over the loan and possibly no mortgage insurance. It also gives you more equity from the start.
- Smaller down payment: you can buy sooner and keep more cash for emergencies, repairs and moving, but pay more each month and in total.
Each $10,000 of extra down payment on a 30-year loan at 6.5% lowers the principal and interest payment by about $63 a month.
Other cash you will need
The down payment is not the only upfront cost. Closing costs commonly add several percent of the loan amount, and lenders may want to see cash reserves after closing. Budget for an inspection, an appraisal, moving costs and immediate repairs. Your Loan Estimate shows the cash to close the lender expects. When you plan with the down payment calculator, add these costs to your savings goal.
Saving for a down payment
Divide what you still need by the number of months until you want to buy to find a monthly savings target: $50,000 over 36 months is about $1,389 a month. Keep the money somewhere safe and easy to reach, such as a high-yield savings account or certificates of deposit timed to your purchase. Check your state or city housing finance agency for down payment assistance programs for first-time buyers. If family members help with a gift, lenders usually require a signed gift letter showing the money does not have to be repaid.
Estimates for education only, not financial advice. Your lender’s figures are final.
Choosing your target
Many buyers set their goal by comparing two or three scenarios. Run the down payment calculator at 5%, 10% and 20%, then use a mortgage calculator to compare monthly payments and mortgage insurance at each level. Choose the lowest down payment that keeps your monthly cost comfortable and still leaves an emergency fund after closing. If prices rise while you save, update the home price so your target stays realistic.
Related converters and calculators
Related calculators:
- Mortgage calculator: payments
- House affordability calculator: affordability
- Closing costs calculator: closing costs
- FHA loan calculator: FHA
Sources
CFPB: What is private mortgage insurance?; HUD Mortgagee Letter 2023-05: Reduction of FHA annual MIP; CFPB: Loan Estimate explainer.
Formula and method
Need = price × pct / 100. Remaining = max(0, need - saved). Headline is the target need.
Percent of price minus optional savings. Not a full affordability or PMI model.
Questions about this calculator
How much is 20% down on $400,000?
$80,000.
Do I need 20% down?
No, but conventional loans with less than 20% down usually require PMI.
What does FHA mortgage insurance cost?
A 1.75% upfront premium plus an annual premium, 0.55% for most 30-year loans with under 5% down.
Are closing costs part of the down payment?
No, they are separate.
Can a gift be used?
Often yes, with a gift letter.
Check the assumptions and units before relying on a result. Financial, tax and health estimates do not replace advice for your individual circumstances.
Report a calculation issue