
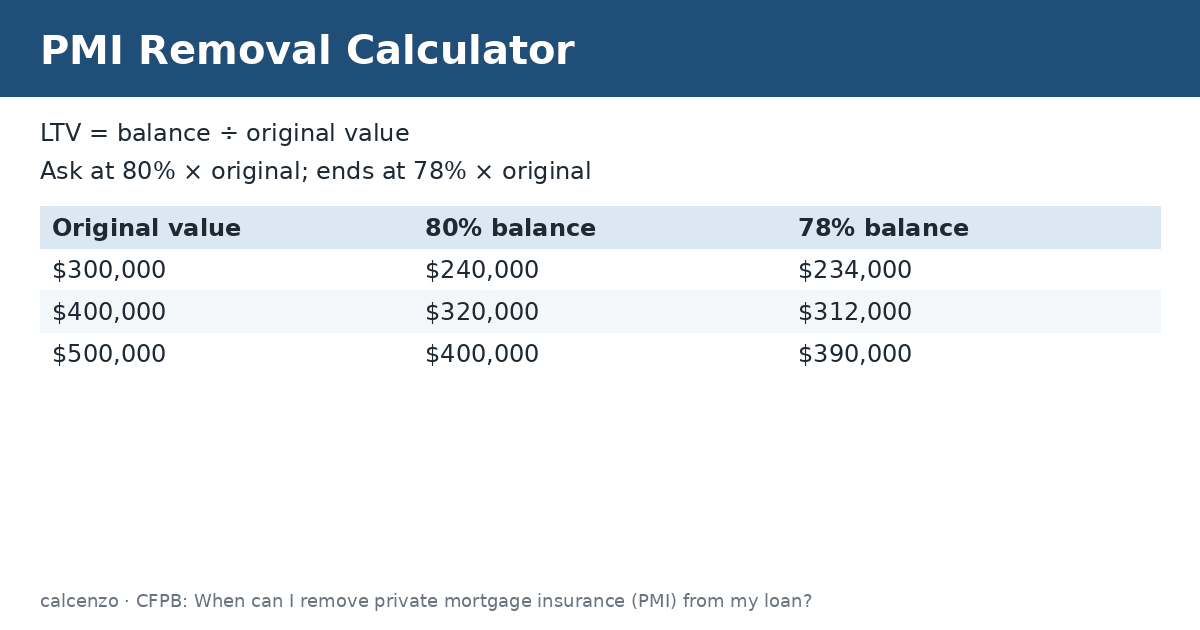
A PMI removal calculator shows how close your loan balance is to the points where you can ask to drop private mortgage insurance or where it must end on its own. Formula: LTV = current balance ÷ original value; request point = 80% × original value; automatic end = 78% × original value. With a $400,000 original value and a $330,000 balance, your LTV is 82.5%; you can request cancellation at $320,000 and PMI must end at $312,000 if you are current.
On this page
How to use the PMI removal calculator
- Enter the original value: the lower of the contract price or the appraisal when you bought, or the appraisal from a refinance.
- Enter your current loan balance from your latest statement.
- Enter a current value estimate or a recent appraisal.
The PMI removal calculator returns your LTV on the original value, LTV on the current value, and the balances that equal 80% and 78% of the original value.
The 80% and 78% rules
According to the CFPB, you have the right to ask your servicer to cancel PMI when your balance is scheduled to reach, or you have paid it down to, 80% of the original value. The request must be in writing, you need a good payment history and be current, you must certify there are no junior liens, and you may need to show the value has not fallen below the original value.
If you do nothing, the servicer must end PMI automatically on the date your balance is scheduled to reach 78% of the original value, as long as you are current. PMI must also end the month after the midpoint of the loan term, which is 15 years on a 30-year loan.
What formula does the PMI removal calculator use?
- LTV on the original value = balance ÷ original value × 100.
- LTV on the current value = balance ÷ current value × 100.
- Request balance = original value × 0.80; automatic balance = original value × 0.78.
PMI removal calculator worked example
Results from the PMI removal calculator:
| Original value | Balance | Current value | LTV (original) | LTV (current) | 80% balance | 78% balance |
|---|---|---|---|---|---|---|
| $400,000 | $330,000 | $420,000 | 82.5% | 78.6% | $320,000 | $312,000 |
| $300,000 | $234,000 | $360,000 | 78.0% | 65.0% | $240,000 | $234,000 |
In the first case you still need to pay down $10,000 to reach the request point. Extra principal payments count, because the CFPB says you can ask early once extra payments bring the balance to 80%. In the second case the balance has reached 78% of the original value, so PMI should end automatically if the loan is current.
Can a higher home value get rid of PMI sooner?
The federal 80% and 78% rules use the original value. Some servicers will also drop PMI based on a new appraisal if your LTV on today’s value is low enough, but that is their policy, not a legal right, and they set the terms. The PMI removal calculator shows the current-value LTV so you know whether the call is worth making.
How to request PMI cancellation
Find the PMI disclosure you received at closing; the CFPB says it should show the first date you can ask. If you cannot find it, call your servicer. Send the request in writing, keep a copy, and ask what proof of value they need. The servicer may order an appraisal at your cost. Make sure you have no late payments in the last year and no second mortgage on the home.
FHA and other loans
These rules apply to private mortgage insurance on conventional loans. FHA mortgage insurance premiums follow FHA’s own rules and often last longer, so check your FHA documents or our FHA loan calculator. VA loans do not carry monthly mortgage insurance.
Estimates for education only, not tax, legal or financial advice. Check current rules with the tax authority or a qualified adviser.
Related converters and calculators
Related calculators:
- Mortgage calculator: monthly payment
- Mortgage payoff calculator: extra payments
- Refinance calculator: refinance option
Sources
CFPB: When can I remove private mortgage insurance (PMI) from my loan?.
Questions about this calculator
When can I ask to remove PMI?
When your balance reaches, or is scheduled to reach, 80% of the original value, if you meet the servicer's conditions.
When does PMI end automatically?
When your balance is scheduled to reach 78% of the original value and you are current on payments.
What counts as the original value?
Usually the lower of the contract price or the appraisal at purchase, or the appraisal at a refinance.
Do extra payments help?
Yes. Paying extra principal can bring you to the 80% point early, and you can ask to cancel then.
Does this apply to FHA loans?
No. FHA mortgage insurance has separate rules.
Check the assumptions and units before relying on a result. Financial, tax and health estimates do not replace advice for your individual circumstances.
Report a calculation issue