
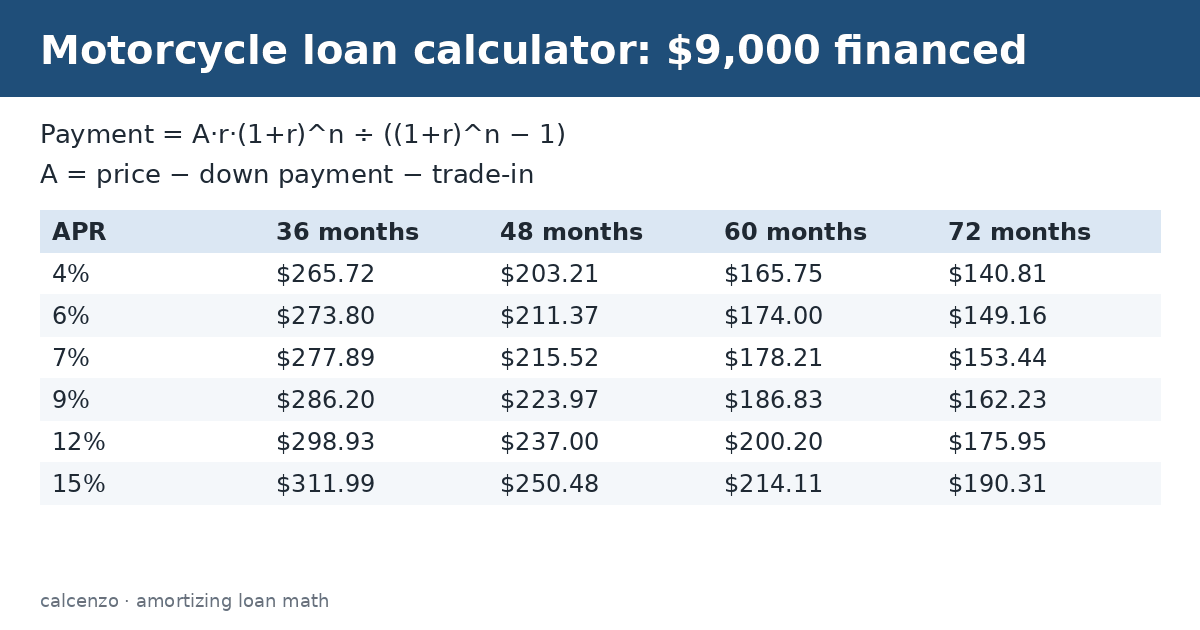
A motorcycle loan calculator estimates your monthly payment from the bike price, down payment, trade-in, APR and term. The motorcycle loan calculator uses this formula: P = price − down − trade. Payment = EMI(P, APR, months). Interest = payment×months − P. For a $10,000 motorcycle with $1,000 down, financing $9,000 at 7% APR for 36 months costs $277.89 a month and $1,004.18 in total interest.
On this page
How to use the motorcycle loan calculator
- Enter the bike price, including fees and tax you will finance.
- Enter your down payment and any trade-in value.
- Enter the APR from your quote and the term in months.
- Read the monthly payment, total of payments and total interest.
What formula does the motorcycle loan calculator use?
- Amount financed (A) = price − down payment − trade-in
- Monthly rate (r) = APR ÷ 12 ÷ 100
- Payment = A × r × (1 + r)^n ÷ ((1 + r)^n − 1), where n is the term in months
At 0% APR the payment is simply A ÷ n.
Motorcycle loan calculator worked example
A $10,000 bike with $1,000 down and no trade-in leaves $9,000 to finance. At 7% APR:
| Term | Monthly payment | Total interest |
|---|---|---|
| 3 years (36 months) | $277.89 | $1,004.18 |
| 4 years (48 months) | $215.52 | $1,344.78 |
| 5 years (60 months) | $178.21 | $1,692.65 |
| 6 years (72 months) | $153.44 | $2,047.76 |
At 12% APR for 60 months the same loan costs $200.20 a month, $21.99 more, which is why your rate matters as much as the price.
Rates, term and credit score
Your APR depends on your credit, whether the bike is new or used, the term and the lender. Shorter terms cost more each month but much less in total. Stretching the term to lower the payment can leave you owing more than the bike is worth, because motorcycles lose value quickly. Compare written APR quotes from a bank or credit union with dealer or brand financing before you choose.
Taxes, fees and dealer add-ons
The advertised price is rarely what you finance. Freight, dealer preparation, documentation fees, sales tax, title and registration can add a meaningful amount. Dealers may also offer add-ons such as extended service contracts, tire-and-wheel protection or GAP coverage. These are optional; if you buy them, add them to the price above so the payment reflects the real loan. The CFPB advises reviewing the contract to see which items are included before you sign.
Credit unions and brand financing
Credit unions often price powersports loans competitively for members. Manufacturer finance arms sometimes advertise low promotional APRs on new models, usually for buyers with strong credit and for shorter terms. A low APR can come with a smaller cash rebate, so compare the total cost of each option.
Ownership costs to budget
Beyond the loan, budget for insurance, riding gear, maintenance, tires and storage. Lenders usually require full coverage insurance while the loan is outstanding, and the premium can be high for new riders or sport bikes. Get an insurance quote before you agree on a price, and add it to the monthly payment to see the real cost of owning the bike. If the total strains your budget, a cheaper or used model, a bigger down payment or a shorter wait to save may be better than a longer loan.
Estimates for education only, not financial advice. Your lender’s figures are final.
48 months versus 72 months
Dealers often quote motorcycle payments on long terms to make the price look smaller. Take $12,000 at 7.9%. Over 48 months the motorcycle loan calculator gives $292.39 a month and $2,034.82 of interest. Over 72 months the payment drops to $209.81, but interest rises to $3,106.57, about $1,070 more.
The longer loan also stays above the bike’s value longer. A motorcycle that loses a good part of its value in the first two years can leave you owing more than it is worth if you crash it or want to sell. Gap coverage helps in a total loss but adds cost, and the motorcycle loan calculator will not show it unless you add it to the amount financed. If the 48-month payment is a stretch, a cheaper bike or a larger down payment may be the better fix. Use the motorcycle loan calculator to test each option.
Related converters and calculators
Related calculators:
- Auto loan calculator: cars
- Boat loan calculator: boats
- RV loan calculator: RVs
- Loan calculator: any fixed loan
- Amortization calculator: full schedule
Sources
CFPB: Auto loans; CFPB: What is amortization?.
Questions about this calculator
How much is the payment on a $10,000 motorcycle?
With $1,000 down at 7% APR for 36 months, about $277.89 a month.
How long can you finance a motorcycle?
Terms of 36 to 72 months are common; longer terms cost more interest.
Are used motorcycle loan rates higher?
Often, yes. Use the APR your lender quotes for the bike you are buying.
Should I finance dealer add-ons?
They are optional. If you buy them, add them to the price so the payment is accurate.
Does the trade-in lower the payment?
Yes. It reduces the amount financed, just like a down payment.
Check the assumptions and units before relying on a result. Financial, tax and health estimates do not replace advice for your individual circumstances.
Report a calculation issue