
A Social Security calculator estimates your monthly retirement benefit from your average earnings and the age you claim. An AIME of $4,000 gives a PIA of $2,025.88 at 67, about $1,418 at 62 and about $2,512 at 70.
On this page
How to use the social security calculator
- Enter your average indexed monthly earnings (AIME).
- Enter the age you plan to claim, from 62 to 70.
- Enter your birth year.
- Read the PIA, claim-age factor and monthly estimate.
How the Social Security calculator works
The Social Security calculator gives an educational estimate of a monthly retirement benefit from two inputs: your average indexed monthly earnings (AIME) and the age you plan to claim, from 62 to 70. It first finds the primary insurance amount (PIA), the benefit at full retirement age, with the SSA formula:
- 90% of AIME up to $1,286
- plus 32% of AIME from $1,286 to $7,749
- plus 15% of AIME above $7,749
These are the SSA bend points for workers first eligible in 2026, meaning they turn 62 that year. It then works out your full retirement age from your birth year and applies the reduction for claiming early or the credit for claiming late.
Social Security calculator worked example
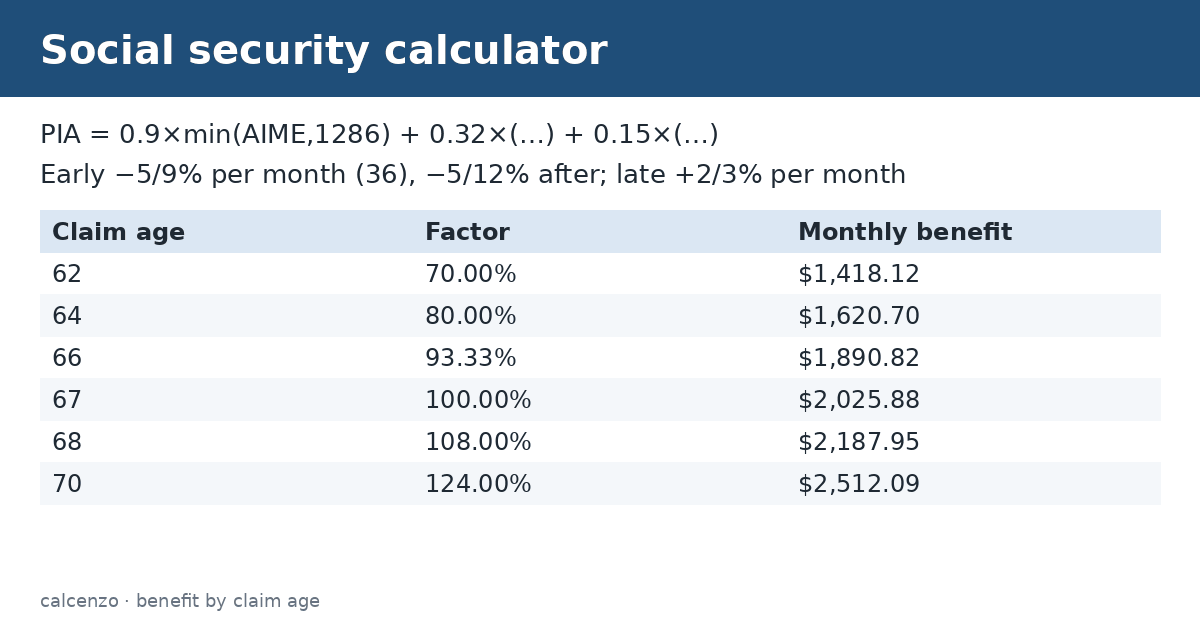
With an AIME of $4,000, the PIA is 0.9 × $1,286 + 0.32 × ($4,000 − $1,286) = $1,157.40 + $868.48 = $2,025.88. Claiming at 67 gives that amount. Claiming at 62 cuts it by 30% to about $1,418, and waiting to 70 raises it by 24% to about $2,512. The Social Security calculator shows the factor and the monthly estimate.
| Claim age | Factor | Monthly benefit |
|---|---|---|
| 62 | 70.00% | $1,418.12 |
| 64 | 80.00% | $1,620.70 |
| 66 | 93.33% | $1,890.82 |
| 67 | 100.00% | $2,025.88 |
| 68 | 108.00% | $2,187.95 |
| 70 | 124.00% | $2,512.09 |
Claiming early or late
For each month before full retirement age, the benefit falls by 5/9 of 1% for the first 36 months and 5/12 of 1% after that, so claiming at 62 with a full retirement age of 67 means a 30% cut. For each month you wait past full retirement age, delayed retirement credits add 2/3 of 1%, or 8% a year, until 70. SSA’s chart confirms the 30% reduction at 62 for people born in 1960 or later.
Full retirement age
The Social Security calculator sets full retirement age from your birth year using the SSA schedule: 66 for 1943 to 1954, then 66 and 2 months for 1955, 66 and 4 months for 1956, 66 and 6 months for 1957, 66 and 8 months for 1958, 66 and 10 months for 1959, and 67 for 1960 or later. For someone born in 1957, claiming at 62 is 54 months early, a cut of 27.5%.
Bend points change every year
SSA updates the bend points each year in line with national average wages. For workers first eligible in 2027, they rise to $1,340 and $8,077. The tool uses the 2026 values, so if you turn 62 in a later year, your PIA will be a little higher than shown for the same AIME. Your AIME itself is based on your highest 35 years of indexed earnings; years with no earnings count as zero.
Getting your official estimate
The best estimate comes from your own record. A my Social Security account shows your earnings history and projected benefits at different ages. Check the record for missing years, since errors lower your benefit. The Social Security calculator is useful for exploring how AIME and claim age interact, not for an exact figure. It ignores cost-of-living adjustments, spousal and survivor benefits, the earnings test and taxes.
Choosing when to claim
Waiting increases the monthly amount for life, which helps if you live a long time and protects a surviving spouse. Claiming early can make sense with health problems or no other income. The social security breakeven calculator compares lifetime totals for different ages.
Tips
- Find your earnings history in a my Social Security account.
- Compare at least three claim ages.
- Remember that your bend points depend on the year you turn 62.
- Use the Social Security calculator alongside your official statement.
Estimates for education only, not financial advice. Your lender’s figures are final.
Related converters and calculators
Related calculators:
- Social Security breakeven calculator: when to claim
- Retirement calculator: savings
- Pension calculator: pensions
- 401(k) calculator: workplace plan
To see how this year’s adjustment changes a benefit, try the Social Security COLA calculator. Medicare premiums can rise with income, which the IRMAA calculator estimates.
Sources
SSA: Primary Insurance Amount formula; SSA: Benefit formula bend points by year; SSA: Starting your retirement benefits early.
Formula and method
PIA = 0.9*min(AIME,1174) + 0.32*max(0,min(AIME,7078)-1174) + 0.15*max(0,AIME-7078). Early: reduce by (5/9)% per month for first 36 months early, then (5/12)% per month. Late: add (2/3)% per month after FRA 67. Benefit = PIA * claim-age factor.
2026 SSA bend points ($1,286 and $7,749) and an FRA-67 claim-age adjustment. Your earnings record, eligibility year and COLAs change the official figure.
Questions about this calculator
How is the PIA calculated?
90%, 32% and 15% of AIME across the bend points.
What are the 2026 bend points?
$1,286 and $7,749.
How much is the cut at 62?
30% when full retirement age is 67.
How much does waiting to 70 add?
8% a year past full retirement age, or 24% at 70.
Is it an official SSA estimate?
No; use your my Social Security account.
Check the assumptions and units before relying on a result. Financial, tax and health estimates do not replace advice for your individual circumstances.
Report a calculation issue